Africa-First • Built for Global Emerging Markets

The Alternative Credit Data Rails for Emerging Markets

Transform unstructured mobile money alerts, airtime top-ups, and utility data into real-time credit-risk scores. Africa is the world's most dynamic mobile-money testbed, making it the ideal launchpad to build and refine alternative credit data rails before expanding across cash-dominant and rapidly digitizing emerging economies in Southeast Asia and Latin America.
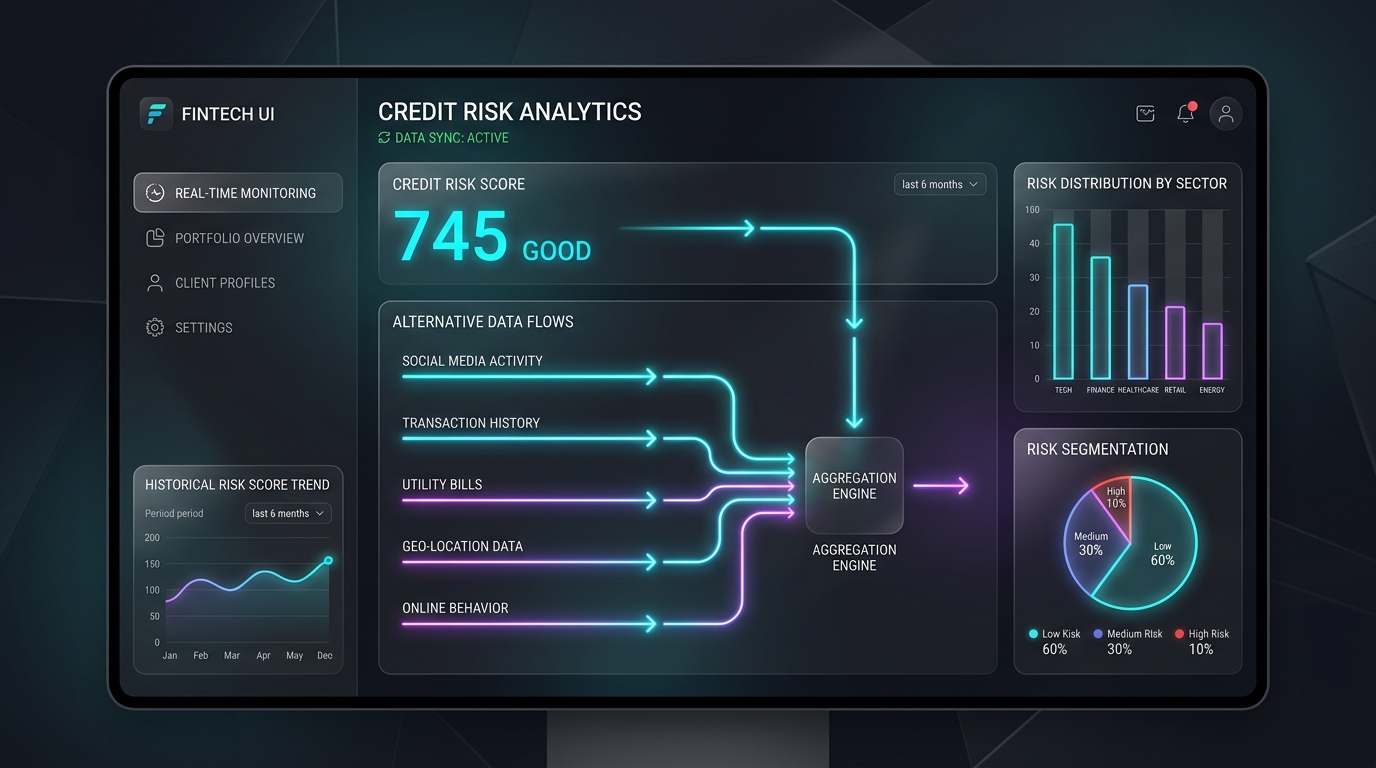
ScoreRails Alternative Credit Data Analytics Dashboard

90%+

Target API Software Gross Margin

2,500+

Target Feature Taxonomy

< 400ms

Sub-400ms API Latency, By Design

1.4 Billion

Global Unbanked Emerging Market TAM

Millions of Creditworthy Consumers Are Invisible to the Financial System

Traditional credit bureaus were built around salaried jobs, bank accounts, and formal loan histories. Most emerging market populations don't fit that model, not because people aren't creditworthy, but because their financial lives happen somewhere bureaus don't look.

What Bureaus See

  • Formal bank account history
  • Salaried payslips
  • Prior bank loan repayments
  • Registered collateral

What ScoreRails Sees

  • Mobile money transaction alerts
  • Airtime top-up frequency
  • Utility payment history
  • Everyday financial behavior, already generated

Our mission is simple: read the financial data people already generate, and turn it into a standardized, explainable credit score, allowing lenders to extend credit responsibly to the customers bureaus overlook.

Built for Modern Lenders

Traditional credit bureaus miss 80% of African consumers. ScoreRails is building alternative credit data orchestration to bridge the vacuum.

Dual-Channel Ingestion SDK

We're designing an embedded Mobile SDK (Android) for smartphones plus a zero-ops USSD Consent Gateway to capture transaction footprints from feature-phone users.

Roadmap

Gemini-Powered Feature Engine

We're building a feature engine on Gemini lightweight models to automatically parse dialectal text, unstructured SMS alerts, and utility bill receipts into structured financial features.

XGBoost Ensemble Scoring Engine

We're developing predictive ensemble ML models to deliver 300–850 credit scores, default probability %, and recommended risk-adjusted loan limits in <400ms.

Open Banking & Wallet Bridge

Designed to align with CBN/NIBSS Open Banking standards and regional mobile money API protocols across West and East Africa (MTN MoMo, M-Pesa, Wave).

Africa-First, Global Potential

Africa is our Pan-African anchor and mobile-money testbed. Our underlying data model is designed to export directly to high-growth emerging markets across Southeast Asia and Latin America.

Explainable AI (XAI) Audit Logs

Engineered to generate transparent, auditable decision reasoning for every score, allowing financial institutions to meet strict NDPC & ODPC central bank requirements.

Built for Emerging Markets, Not Retrofitted for Them

Most alternative-data scoring tools were built for mature economies and adapted later. ScoreRails is built for the dual reality of emerging markets—spanning cash-heavy informal commerce and mobile-first digital transactions—from day one.

Dimension Traditional Bureaus Generic Alt-Data Scorers ScoreRails
Population Coverage Formally banked consumers only Broad, but not tuned to cash-heavy or mobile-first economies Built for unbanked & underbanked majorities
Core Data Sources Bank accounts, formal loan records Device metadata, social signals Mobile money alerts, airtime top-ups, utility payments
Score Explainability Opaque bureau score Often a black-box model Auditable reason codes with every score (XAI)
Regional Compliance Not applicable to unscored population Designed around other regulatory regimes Designed around NDPA, CBN, and Kenya ODPC requirements
Integration Manual bureau pulls, slow onboarding Heavy SDKs, multi-region rework One REST API, lightweight consent widget

Test the Credit Risk Simulator

Adjust alternative consumer data signals below to see how the ScoreRails algorithm calculates creditworthiness in real time.

Alternative Signal Inputs

Monthly Mobile Money Volume ₦150,000
Airtime Top-Up Frequency 12 top-ups/mo
Utility Payment On-Time History 90% on-time
745
EXCELLENT RISK PROFILE

2.1%

Est. Default Probability

₦220,000

Rec. Credit Limit

Developer-First Architecture

Clean REST APIs, lightweight mobile SDKs, and transparent XAI audit reasoning payload.

POST /v1/score
curl -X POST https://api.scorerails.space/v1/score \ -H "Authorization: Bearer sr_test_YOUR_API_KEY" \ -H "Content-Type: application/json" \ -d '{ "phone": "+234XXXXXXXXXX", "bvn_hash": "sha256_hash_of_consented_bvn", "consent_timestamp": 1786616800 }'

Co-Founders

Building alternative credit infrastructure for emerging markets from the ground up.

Tovieye Ozi

Co-Founder & Software Architect

8+ years of professional software engineering experience across JavaScript and Clojure. Focused on clean, simple, effective solutions to engineering problems, with a particular interest in working with data — transforming and flowing it through production systems.

ozimos

Dienebi Ombu

Co-Founder & Strategy / Growth

Experience across enterprise software development, data systems and databases, and government digital systems — including production information systems built for public-sector institutions — alongside applied data and AI work.

ebidien
Early Access Waitlist

Join the ScoreRails Waitlist

We are taking down contact info for interested financial institutions, digital lenders, and developer teams. Register below to be notified as we roll out updates.